Waterloo Region Real Estate & Living

Guiding You Home, Every Step of the Way

Welcome to the Magnolia Group Realty blog, where Waterloo Region real estate meets real life at home.

Whether you're thinking about buying, preparing to sell, trying to understand what the latest market numbers actually mean, or simply looking for ways to take better care of the home you already love, you'll find practical advice here without all the unnecessary real estate jargon.

Explore local Waterloo Region market updates, home buying and selling guidance, neighbourhood and community stories, and straightforward homeowner advice designed to help you make smarter decisions about your home.

You'll also find Homeowner Tips for tackling those little jobs that come with owning a home, Grime & Shine for cleaning tricks, recipes and solutions worth keeping, and Magnolia Living, our guide to events, local favourites and things worth discovering throughout Waterloo Region and beyond.

Because home isn't only about what it's worth or when you bought it. It's where you live your life, make your messes, fix the things that mysteriously stopped working, invite people over and occasionally Google “is my furnace supposed to make that noise?”

Come for the real estate. Stay for everything that makes a house feel like home.

RSS

No housing market meltdown in sight despite Trump tariff threats

CMHC projects home sales, prices will rebound in 2025 – but more severe tariffs than expected could complicate the picture
No housing market meltdown in sight despite Trump tariff threats

By Fergal McAlinden
05 Feb. 2025

Falling mortgage rates and new mortgage rule changes are expected to help spark a rebound in home prices and sales in the coming years, although the recovery could be an uneven one – and housing starts are set to continue slowing between now and 2027.

That’s according to Canada Mortgage and Housing Corporation (CMHC), whose housing market outlook for the year ahead highlighted the “significant uncertainty” to the Canadian economy of threatened US tariffs but said improving affordability would boost homebuyer prospects in its medium scenario for a potential trade war.

That projection assumes US tariffs of 25% on 10% of Canadian goods and retaliatory measures by Canada, with lower immigration in the coming years also likely to contribute to “modest” economic growth this year before improving in 2026 and 2027.

But a tariff dispute of that intensity wouldn’t crater Canada’s housing market, CMHC suggested. “Despite the economic headwinds… we expect housing market activity in Canada to improve,” the agency’s top economists wrote. “The combination of lower mortgage rates and changes to mortgage rules introduced in 2024 should unlock pent-up demand from homebuyers previously priced out of the market.

“However, some of these homebuyers may face longer loan terms, higher interest costs over the duration of the loan and larger downpayments as prices continue to rise.”

The federal government tweaked mortgage rules last year to allow expanded access to 30-year amortizations for first-time buyers and Canadians purchasing newbuilds, while it also hiked the insured mortgage cap to $1.5 million in a bid to improve purchasing power.

Millennials are likely to remain a key driver of housing demand in 2025, CMHC said, with a decline in remote work and stepping up of companies’ return-to-office efforts potentially seeing that buyer cohort prioritize being closer to jobs and boosting sales in large urban markets.

Affordability challenges show no signs of easing in major cities

However, the affordability picture isn’t positive across the board. CMHC’s report said Alberta and Quebec would see sales reach “historically high levels” with prices potentially surging – but Ontario and British Columbia sales could stay below 10-year averages because of current eyewatering home prices and the outsized impact there of lower immigration.

The condo market’s struggles also show little sign of easing. Activity in that sector is projected to continue lagging – particularly in regions more dependent on investor activity. “Investors who bought pre-construction units to rent out are increasingly selling as costs rise faster than rental incomes,” CMHC said.

“We expect listings to continue to increase, driven by record new condominium apartment completions in 2025 and softening rental markets.”

Millions of new units are required by 2030 to restore affordability across Canada’s housing market, but housing starts are projected to slow further in the years ahead, according to CMHC.

While starts are set to remain above their 10-year average, that slump in condo construction is expected to weigh heavily against the construction outlook as investor interest wanes and families turn toward more “family-friendly” properties.

Tariff threat continues to loom large over Canada’s economy

CMHC’s medium expectation for a trade war would see the housing market stave off threats of a crash – but its worst- and best-case scenarios don’t exactly suggest a housing meltdown is imminent, either.

Higher tariffs on Canadian exports could see job losses and a 2025 recession, the agency said, while a trade war could result in a short-term jump in inflation but a lower Bank of Canada policy rate to boost the economy.

While a recession would delay a housing market recovery, it would also see pent-up demand swell, according to CMHC. Fewer homes may be built, but the economy would be likely to rebound by the end of 2026 as population growth spurs further sales.

In the opposite scenario, in which the US would impose milder and short-lived tariffs, higher incomes and stronger consumer confidence could boost spending. In that case, “stronger declines in borrowing costs make homeownership more attainable,” CMHC’s report said.

“More homes are built thanks to better financing and business conditions. Stronger job and income growth combined with lower mortgage rates make homeownership more accessible. Higher demand pushes home prices up more quickly.”

The depth and severity of potential US tariffs remains to be seen, with US president Donald Trump and Canada’s prime minister Justin Trudeau striking a deal on Monday to stave off a trade war for at least 30 days.
Read

Trump pausing Mexico tariffs – is Canada next?

Ontario premier says Canadian officials doing 'everything they can' to convince US to drop Canada tariffs

Trump pausing Mexico tariffs – is Canada next?

By Fergal McAlinden

03 Feb. 2025

Mexican president Claudia Sheinbaum said Donald Trump has agreed to pause 25% tariffs on her country for a month, while Canadian prime minister Justin Trudeau is scheduled to speak with the US president for the second time today at 3:00 p.m. ET.  

Sheinbaum said she had had a “good conversation” with Trump on Monday morning, resulting in a delay to the massive levies announced by the White House that were scheduled to come into effect tomorrow (February 4). 

Trump had accused Sheinbaum’s government of entering an “intolerable alliance” with Mexican crime gangs, triggering a sharp rebuke from Mexico’s president – but she said today she has reached a number of agreements with Trump including the dispatchment of 10,000 Mexican national guard members to the border to clamp down on drug trafficking.  

The news has sparked speculation that Trudeau will call for a similar delay to Trump’s tariffs on Canada, which are also set to take effect tomorrow. On Saturday, Trump announced 25% levies on all Canadian imports to the US except energy, which was charged at 10%.  

Trudeau responded with countermeasures on US products entering Canada, introducing 25% tariffs on billions of dollars’ worth of American imports to the country.  

The trade spat has roiled markets and raised fears of a recession, with National Bank of Canada arguing the crisis could call for an emergency oversized rate cut by the Bank of Canada in the weeks ahead.  

Trudeau spoke with Trump this morning, and Ontario premier Doug Ford said he hopes the US president will follow his reversal on Mexico with a similar decision on Canadian tariffs.  

“We’re their number one customer. We’re their number one export destination,” Ford said on Monday, indicating Canadian officials were doing “everything they can” to reach an agreement with the US.  

“We’re working governor to premier, premier to senator and congresspeople, and all premiers are doing it. They’re reaching out to their counterparts,” he said. “And we’re doing our job. And I know the prime minister is doing his job by contacting President Trump today and later this afternoon.  

“That decision President Trump has made is so, so misguided. He underestimates the power and the will and the fortitude of Canadians. We’re their closest trading partner and ally.”  

Read

How will Trump's tariffs impact Canada's housing market?

Canada enters a new reality this week after huge US levies on Canadian imports

How will Trump's tariffs impact Canada's housing market?

By Fergal McAlinden

03 Feb. 2025

It’s been the single biggest imponderable looming over the Canadian economy in early 2025 – and US tariffs became a reality on Saturday when Donald Trump introduced massive charges on Canadian goods crossing the border southwards.

That action, which includes 25% levies on all Canadian imports excluding energy – which was tariffed at 10% – has cast huge uncertainty over Canada’s economic outlook and sparked fears of a potential hammer blow to the loonie.

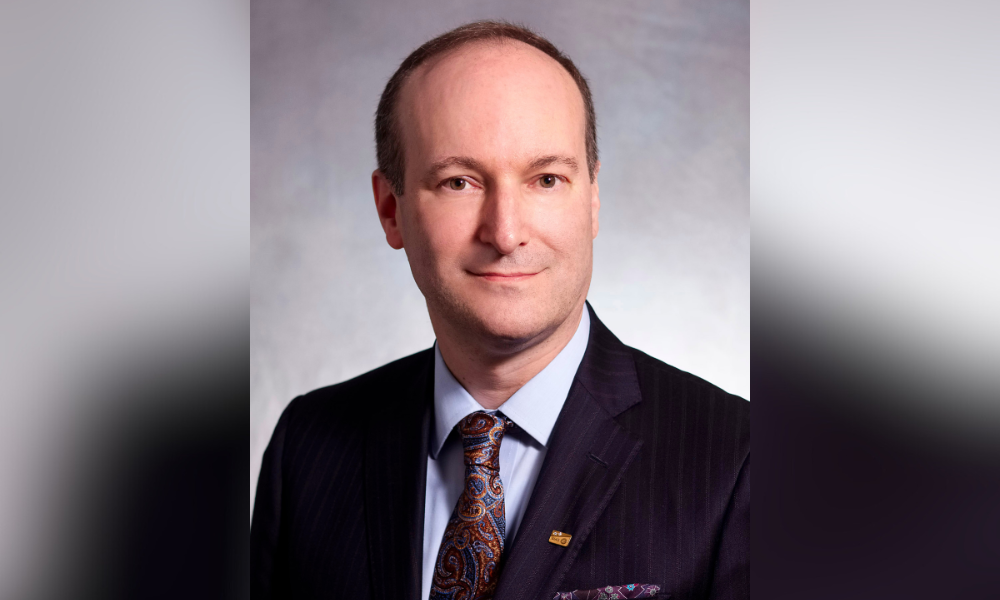
Its effect on Canada’s housing market remains to be seen. Last week, Bank of Montreal (BMO) chief economist Doug Porter (pictured top) told Canadian Mortgage Professional that the Bank of Canada would likely slash interest rates further if US tariffs began to weigh down heavily on the Canadian economy, meaning potential borrowing costs could end up even lower than first anticipated for the year ahead.

But the severity of Trump’s measures – and Canada’s response, which included retaliatory tariffs on billions of dollars’ worth of American goods – leaves plenty in doubt about whether the housing market will suffer from wider economic strain.

Intensity of potential trade war remains a key unknown

Speaking days before Trump confirmed the tariffs would go ahead, Porter suggested a “light trade war” could boost the Canadian housing market, but emphasized it would probably be damaged by anything more intense.

“Even though the Bank is a bit mixed [on being prepared to cut rates], I think at the end of the day it means lower interest rates than would otherwise be the case,” Porter told Canadian Mortgage Professional. “And of course, the housing market is the most interest rate-sensitive sector of the economy. In general, I don’t think a trade war would have much direct impact.

“What I would be worried about is if the Canadian economy were really wounded badly by a trade war, then that could actually work its way back into the housing market and clip demand as well. The threat to the housing market would be the indirect effect of a weaker economy.”

After the tariffs were announced, Porter said the trade war would likely reduce Canada’s GDP growth by around two percentage points and could slide the economy into a “modest recession” if those measures remained in place for a year.

The Bank of Canada is also likely to slash its policy rate by a quarter-point at every meeting until October, he said, bringing it down from its current level to 1.5%.

US tariffs and countermeasures are likely to see the cost of materials for home construction jump on both sides of the border. But Porter said that wouldn’t necessarily harm Canada’s housing outlook significantly.

“Some building materials could face tariffs, when you think of things like plumbing supplies. But a lot of things can be produced here too or already are produced here,” he said. “The costliest part of building a house is land and labour – less so some of the supplies. So I don’t think it will have too negative an effect on the housing market.”

How is the housing market poised after the BoC’s actions to date?

US president Donald Trump first announced the tariff plans in November, a bolt out of the blue that roiled markets and sent the Canadian dollar plunging.

The reasons Trump has given for those proposed measures have varied. Initially, he claimed Canada’s border security was too lax, while last week he said Canada and Mexico “have never been good” to the US on trade matters.

His claims have been refuted by observers including former Canadian prime minister Stephen Harper, who said he had a “real problem” with some of Trump’s pronouncements on Canada.

Those threats have been mentioned in each of the Bank of Canada’s last two interest rate announcements, a 50-basis-point cut in December and a quarter-point snip last week.

The Bank’s statement after reaching its decision on Wednesday noted the resilience of the Canadian economy could come under strain with the imposition of “broad-based and significant” US tariffs.

That rate reduction alone will do little to spur activity in Canada’s housing market, Porter said, although he sounded a positive overall note on its 2025 prospects despite the prospect of lower immigration this year than first planned.

“We’ve now had two percentage points of total easing by the Bank of Canada [since last June],” he said. “That’s a very aggressive move by the Bank in a short period of time, and a clear positive for the housing market. Heading into this, the housing market looked as if it was getting back on its feet. I wouldn’t say it was strong, but it was relatively well-balanced.

“It has had the very strong population growth support knocked out from underneath it – but I think interest rates are a more important story for the housing market. I’d still be mildly constructive on the housing market this year, even with the threat of a trade war.”

Read

Refinancing Your Mortgage in 2025.

Refinancing your mortgage can be a smart financial move for many reasons, and as your trusted mortgage advisor, I’ve seen how much it can benefit homeowners!

Ideally, refinancing is done at the end of your mortgage term to avoid penalties, but the timing can vary depending on your goals. For some, it’s about unlocking the equity in their home to fund renovations or cover big expenses like college tuition. For others, it’s an opportunity to consolidate debt, lower their interest rate, or change up their mortgage product.

Let’s take a closer look at some of the ways refinancing your mortgage can help!

  • Get a Better Rate: As interest rates have continued to decrease with the Bank of Canada updates these past few months, now is a great time to consider refinancing for a better rate and lower overall mortgage payments!  Experts anticipate the Bank of Canada will move to have the overnight rate down to 4.0% at year-end and potentially down to 2.75% for 2025.

  • Consolidate Debt: When it comes to renewal season and considering a refinance, this is a great time to review your existing debt and determine whether or not you want to consolidate it onto your mortgage. In most cases, the interest rate on your mortgage is less than you would be charged with credit card companies or other forms of financing you may have. Plus, having all your debt consolidated into a single payment can keep you on track!

  • Unlock Your Home Equity: Do you have projects around the house you’ve been dying to get started on? Need funds for a large purchase such as a new vehicle or post-secondary education? When you are looking to renew your mortgage, it is a great opportunity to consider refinancing in order to take advantage of the home equity you have built up to help with these larger changes in your life!

  • Change Your Mortgage Product: Are you unhappy with your existing mortgage product? If you have a variable-rate or adjustable-rate mortgage, you may be considering locking it in at the lower rates. Alternatively, you may want to switch your current fixed-rate mortgage to a variable option with the interest rates expected to continue decreasing into 2025. You can also utilize your refinance to take advantage of a different payment or amortization schedule to help pay off your mortgage faster!

PLUS! Some latest changes by the Government of Canada will make it even easier for you when it comes to your renewal and refinancing options:

  • Those of you who may have an uninsured mortgage will no longer have to pass the stress test as of November 21st. This means that you have more flexibility when it comes to rates and mortgage products in renewal cases where you wish to switch lenders without adding additional funds to your mortgage!

  • Beginning January 15, the federal government will allow default-insured mortgages to be refinanced to build a secondary suite. If you’ve been considering adding a suite to your property, you may be eligible to access up to 90% of your home’s equity for this purpose.

No matter your plans or situation, please don’t hesitate to reach out to a DLC Mortgage Expert! Our own Charlotte Ferguson is a licensed Mortgage Agent, Level 2, and is happy to help!  https://yourmagnoliagroup.ca/MortgageAgent

Read

Bank of Canada cuts rates in first decision of 2025

Inflation, labour market and Trump threats all hovered over central banks’ January move

By Fergal McAlinden
29 Jan. 2025

The Bank of Canada has lowered its benchmark rate again, making a sixth consecutive cut amid continuing signs of a slowing economy and falling inflation.

The central bank said on Wednesday morning that it had trimmed the key rate by 25 basis points, a move that brings it to 3% but also marks a smaller reduction than its previous two cuts.

That decision arrives after the annual inflation rate dropped to 1.8% in December, just below the Bank’s 2% target, spurred in large part by the federal government’s temporary GST break.

Without that tax break, overall inflation would have jumped to 2.3% – but while the labour market appeared to strengthen in December, adding a better-than-expected 91,000 jobs, the threat of tariffs on Canada by new US president Donald Trump kept a January rate cut firmly on the table.

Bank decisionmakers slashed rates by 50 points in both October and December, with governor Tiff Macklem describing Trump’s tariff threats as a “major new source of uncertainty” last month and underlining the potential they posed for significant disruption to both the US and Canadian economies.

The president has doubled down on threats to introduce tariffs on Canadian goods crossing into the US, saying he’ll impose the measures beginning on February 1 in line with similar levies against Mexico.

Economists have warned of the huge negative impact that move could have on the Canadian economy, although whether or not Trump plans to follow through with the threat remains unclear.

Bank of Canada’s benchmark continues to tumble from 23-year high

The Bank of Canada’s benchmark rate has now fallen by a full two percentage points since the middle of last year. The central bank introduced a flurry of rate hikes throughout 2022 and 2023 in a bid to curb a spike in inflation – and after holding that rate steady at 5.0% for nearly a year, its highest level since 2001, it began cutting last June.

Macklem indicated in December that the Bank was likely to begin moving at a more cautious pace in 2025, although Trump’s threats could now weigh heavily in the central bank’s thinking as it maps out its approach for the months ahead.

The Bank is scheduled to announce its next decision on rates on March 29, followed by six further decisions throughout the year.

Read

Understanding the Mortgage Pre-Approval Process in Ontario | Magnolia Group Realty

Understanding the Mortgage Pre-Approval Process in Ontario | Magnolia Group Realty

When you're ready to purchase a home, getting a mortgage pre-approval is one of the first and most important steps in the home-buying process. Whether you're a first-time homebuyer or have experience in real estate, securing pre-approval will give you a clear idea of your budget and streamline your search. At Magnolia Group Realty, we’re here to guide you through the mortgage pre-approval process and help you make informed decisions. Here's everything you need to know to start your journey with confidence.

1. What is a Mortgage Pre-Approval?

A mortgage pre-approval is a formal commitment from a lender that outlines how much they are willing to lend you for a home purchase, based on your current financial situation. Unlike pre-qualification, which is an estimate, pre-approval requires you to provide documents verifying your income, credit score, assets, and debts. Once your lender verifies this information, they can give you a pre-approved loan amount, which is often valid for 60 to 120 days.

Having a pre-approval gives you insight into your buying power and helps you avoid looking at homes outside your budget. It also shows sellers that you’re a serious buyer and ready to make a purchase.

2. How Does the Pre-Approval Process Work?

The pre-approval process is straightforward, but it requires you to gather important documents and undergo a review of your financial status. Here's how it works:

Step 1: Prepare Financial Documents

You'll need to gather documents to verify your financial situation, such as:

  • Proof of identity (driver's license, passport)

  • Proof of income (pay stubs, tax returns, employment verification)

  • Details of any existing debts (credit cards, car loans, etc.)

  • Bank statements

  • Your down payment amount (or plan)

Step 2: Complete a Mortgage Application

You’ll complete a mortgage application, which can usually be done online or in-person. The application will ask for personal and financial information, and once submitted, it will be assessed by a lender.

Step 3: Lender Reviews Your Financial Information

The lender will analyze your application, assessing factors like your debt-to-income ratio and credit score. They’ll consider how much you can afford to borrow and your ability to repay the loan. Once approved, they will send you a pre-approval letter.

Step 4: Receive a Pre-Approval Letter

Once your lender verifies your financial information, they’ll issue a pre-approval letter. This letter specifies how much you can borrow, your monthly payments, and your interest rate (which could be fixed or variable). Keep this letter on hand, as it will help you determine your price range.

3. Why Should You Get Pre-Approved?

Here are some of the key benefits of mortgage pre-approval:

  • Clarity on Your Budget: A pre-approval gives you a clear understanding of how much you can afford, which ensures you don’t waste time looking at properties out of your price range.

  • Greater Confidence: You’ll feel more confident making offers when you know your mortgage has already been approved, making the process smoother and faster.

  • Competitive Advantage: In Ontario's competitive market, a pre-approval letter demonstrates to sellers that you are a serious, financially capable buyer, giving you an edge over other offers.

  • Speeding Up the Process: With a pre-approval in place, you’ve already completed a significant portion of the application process. This can shorten the time it takes to finalize the mortgage once you’ve found your home.

4. What Happens After Pre-Approval?

After you’ve received your pre-approval, you can begin searching for homes within your price range. But don't forget to keep in touch with your lender throughout the process, especially if there are any changes in your financial situation. If there are adjustments to your income, debt, or expenses, it’s important to keep your lender updated to avoid issues at closing.

5. Tips for a Successful Pre-Approval Process

  • Maintain a Good Credit Score: Before applying, ensure your credit score is in good shape to improve your chances of a better interest rate.

  • Pay Down Debt: Reduce your debts to improve your debt-to-income ratio, which will make you more attractive to lenders.

  • Avoid Large Purchases: Don’t make major purchases or take on new debts during the pre-approval process to avoid disrupting your financial stability.

6. Partnering with a Mortgage Expert

A successful mortgage pre-approval process often involves the expertise of a licensed professional. If you’re ready to take the next step in securing financing, Charlotte Ferguson is a licensed Mortgage Agent, Level 2 with DLC National Ltd. Charlotte provides personalized guidance tailored to your needs, ensuring you understand your financing options and can confidently move forward with purchasing your new home. Connect with Charlotte today and get started on your mortgage journey: https://tinyurl.com/CharlotteFergusonMortgages.

Read

Affordable Housing Options in Ontario: A Comprehensive Guide | Magnolia Group Realty

Affordable Housing Options in Ontario: A Comprehensive Guide | Magnolia Group Realty

Ontario’s real estate market has gained a reputation for being fast-paced and expensive. However, it’s still possible to find affordable housing options, especially with some knowledge of the available programs and areas where your budget can stretch farther. At Magnolia Group Realty, we’re committed to guiding you through the real estate landscape in Ontario to help you find an affordable option that fits your budget and needs. Whether you’re a first-time homebuyer or looking to downsize, here’s an in-depth guide to affordable housing in Ontario.

1. Affordable Housing Programs in Ontario

Ontario offers several programs to assist residents with purchasing a home or renting at more affordable rates. Here’s a look at the most popular programs designed to make housing more accessible:

First-Time Home Buyer Incentive

The First-Time Home Buyer Incentive is a shared-equity program that offers 5% or 10% of the purchase price of a new or resale home. This helps to reduce your monthly mortgage payments without increasing your down payment. It’s available to eligible first-time buyers who meet certain income and purchase price thresholds.

Land Transfer Tax Refund

First-time homebuyers in Ontario are eligible for a refund of up to $4,000 of the land transfer tax. This can help reduce upfront costs and make the initial purchase of your home more affordable.

Ontario Home Ownership Savings Plan (OHOSP)

Although this program is now closed, it may still be worth looking into any similar regional programs available in Ontario. Historically, the OHOSP allowed first-time homebuyers to contribute up to $2,000 annually in a tax-deferred savings account, which they could use towards the purchase of their first home.

Rent-Geared-to-Income (RGI) Housing

Rent-Geared-to-Income (RGI) housing is a type of subsidized rental housing available for lower-income residents. In these units, your rent is based on your income, meaning that as your income changes, so does the amount you pay. These units are available across Ontario and often administered by local municipalities or housing authorities.

2. Low-Cost Housing Areas in Ontario

While real estate in major cities like Toronto, Ottawa, and Mississauga may seem out of reach for many homebuyers, there are several regions in Ontario where property prices remain relatively low and affordable. Some affordable cities and towns to consider include:

Kitchener-Waterloo

Known for its growing tech scene and quality of life, the Waterloo Region offers affordable housing compared to Toronto or Ottawa. Kitchener and Waterloo also offer a vibrant arts, culture, and education scene with access to major highways, making them appealing for young professionals and families.

Sudbury

If you’re looking for an option in Northern Ontario, Sudbury may be the perfect solution. Known for its natural beauty and thriving mining sector, Sudbury offers homes at a fraction of the price of southern Ontario cities while still offering great community resources and services.

Thunder Bay

Another Northern Ontario city, Thunder Bay, offers a low cost of living, access to nature, and strong community ties. Housing prices in Thunder Bay are more affordable, making it a great option for first-time buyers or anyone looking to downsize.

Kingston

With a lower cost of living compared to nearby cities such as Ottawa, Kingston offers affordable housing while providing access to cultural attractions, outdoor activities, and university communities.

3. Affordable Rental Options

If buying a home is out of your budget, renting is an alternative option. However, finding affordable rental properties can also be a challenge in Ontario’s competitive market. Keep an eye out for options in smaller towns or neighborhoods on the outskirts of larger cities where the rent may be lower.

Renting in Smaller Communities

Renting in smaller communities outside major city centers can offer much more affordable options. For instance, in places like Brantford, Stratford, and Peterborough, rent for apartments, houses, or duplexes is significantly less than it would be in the core of Toronto or Ottawa.

Student Housing

Many of Ontario’s universities, like Queen’s University in Kingston or University of Waterloo, offer affordable student housing options for both local and international students. If you’re just starting out or looking for a rental near educational institutions, you may want to explore student housing options that offer budget-friendly rates.

4. Consider Home Sharing or Co-Ownership

In a higher-priced market, many young homebuyers are turning to creative alternatives like home sharing and co-ownership. These options can significantly reduce the upfront and monthly costs of homeownership while providing benefits like shared responsibilities and costs.

  • Home Sharing: Home sharing involves partnering with another person or family to split the costs of purchasing and maintaining a property. This can be particularly effective for families or individuals looking to enter the market who might otherwise struggle with down payments.

  • Co-Ownership: Another model becoming popular in Ontario is co-ownership, where two or more people go in together on a home purchase. This enables buyers to share expenses like mortgage payments, utilities, and maintenance fees while still enjoying the benefits of ownership.

5. Tips for Navigating Ontario’s Real Estate Market

  • Work with a Local Realtor: At Magnolia Group Realty, we have deep knowledge of Ontario's local markets and can help you find affordable properties that meet your needs, whether you're buying or renting. A local real estate expert can provide valuable insights and guide you to regions that offer better value for your money.

  • Get Pre-Approved: Before starting the home search, make sure to get pre-approved for a mortgage. This will help you understand your budget and narrow your home search to properties that fit within your price range.

  • Look for Up-and-Coming Neighborhoods: Some areas may have properties that are still undervalued but are on the verge of growth. Working with a real estate agent who knows the emerging markets can lead to finding a hidden gem for your future.

Conclusion: Finding Affordable Housing in Ontario

The Ontario housing market can feel overwhelming, but with a clear understanding of your options, it’s still possible to find a home that fits your budget. Whether you’re looking into government programs, exploring low-cost areas outside of big cities, or considering alternatives like co-ownership, there are ways to make homeownership or renting more affordable. With Magnolia Group Realty by your side, you can confidently navigate the market and secure an affordable housing option in Ontario.

Read

Fixed Rate vs Adjustable Rate Mortgages in Ontario: Which is Right For You? | Magnolia Group Realty

Fixed Rate vs Adjustable Rate Mortgages in Ontario: Which is Right For You? | Magnolia Group Realty

When it comes to buying a home in Ontario, choosing the right mortgage is one of the most important financial decisions you'll make. Two of the most popular types of mortgages are fixed rate and adjustable rate mortgages (ARM), each offering distinct advantages depending on your financial situation and long-term goals. At Magnolia Group Realty, we understand that understanding the differences can help you make an informed decision. Let’s break down the key differences between fixed rate and adjustable rate mortgages, and which might be the best fit for you.

1. Fixed Rate Mortgage: Stability and Predictability

A fixed rate mortgage locks in your interest rate for the entire term of the loan, typically 5, 10, or even 25 years. This provides homeowners with predictability and a consistent payment schedule, making it a popular choice among Ontario buyers, particularly those who prefer a stable financial outlook.

Advantages of Fixed Rate Mortgages:
  • Consistency: With a fixed rate mortgage, your monthly payments will remain the same throughout the life of the loan, regardless of interest rate fluctuations in the market. This makes budgeting easier, especially for those with tight or predictable income streams.

  • Protection from Interest Rate Increases: If you secure a fixed rate in a market where rates are low, you are insulated from interest rate hikes, which can save you a significant amount of money over time.

  • Long-Term Planning: A fixed rate mortgage provides the stability necessary for long-term homeownership planning. If you’re planning to stay in your home for an extended period, the fixed rate might be an ideal option to consider.

Disadvantages:
  • Higher Initial Rates: Fixed rate mortgages often come with higher interest rates than adjustable rate mortgages, especially in a low-rate environment.

  • Less Flexibility: If market rates drop significantly, you may end up paying more than necessary, as your rate is locked for the duration of the term.

2. Adjustable Rate Mortgage (ARM): Flexibility for Market Conditions

An adjustable-rate mortgage features an interest rate that is linked to a benchmark or index, such as the prime rate or the Bank of Canada’s overnight lending rate. Initially, ARMs may offer a lower interest rate compared to fixed rate mortgages, making them appealing to buyers who anticipate moving before their rate adjusts or those looking for short-term savings.

Advantages of Adjustable Rate Mortgages:
  • Lower Initial Rates: Since ARMs are tied to the market, they often have lower initial rates than fixed rate mortgages, which can make them attractive for buyers looking to maximize their purchasing power or for those buying a home that they don’t intend to stay in long-term.

  • Potential Savings If Rates Stay Low: If the market rates remain low or continue to decrease, you might benefit from lower monthly payments.

  • Flexibility: For buyers who anticipate selling or refinancing in a few years, an adjustable-rate mortgage allows them to take advantage of a lower initial rate without worrying about interest rate changes over the long term.

Disadvantages:
  • Risk of Higher Payments: After the initial fixed period (usually 3, 5, or 7 years), your interest rate may adjust, and monthly payments could increase, especially if interest rates in the market rise.

  • Uncertainty: For long-term homeowners, this uncertainty may be less attractive, particularly in a rising interest rate environment.

3. Which Mortgage Is Right For You?

The right choice depends largely on your financial goals and personal preferences. Here are a few questions to ask yourself as you weigh your options:

  • How long do you plan to stay in your home? If you're planning to stay in the property for many years, a fixed rate mortgage may offer the security and predictability you're looking for. If you're planning to sell or refinance in a few years, an adjustable rate mortgage may provide short-term savings.

  • Do you prefer stability or are you comfortable with some uncertainty? Fixed-rate mortgages provide long-term certainty, while adjustable-rate mortgages offer the possibility of adjusting to market conditions for either higher or lower monthly payments.

  • What is the market like in Ontario? If mortgage rates are currently high and expected to go down, an ARM may be appealing as it could lower your initial payments. If rates are expected to rise, a fixed-rate mortgage offers protection.

4. Consulting with a Mortgage Specialist

Choosing between a fixed rate and an adjustable rate mortgage can be a complex decision, especially when factoring in future market conditions and your own financial situation. At Magnolia Group Realty, we can help connect you with trusted mortgage brokers who can provide expert guidance in choosing the best mortgage option for your home purchase in Ontario. Having the right professional advice makes the home-buying process smoother and ensures you choose the mortgage type that best suits your needs.

Conclusion: Make an Informed Decision

Your mortgage choice plays an important role in your long-term financial health, and it's essential to consider both your current situation and future plans. Whether you decide on a fixed-rate mortgage for predictable, long-term payments, or an adjustable-rate mortgage for a potentially lower rate in the short term, it's critical to do your research and talk with professionals.

At Magnolia Group Realty, we’re committed to helping you make the best decision for your real estate goals. Contact us today to start your home-buying journey with the right financial foundation!

Read

Integrating Smart Home Technology in Ontario Real Estate | Magnolia Group Realty

Integrating Smart Home Technology in Ontario Real Estate | Magnolia Group Realty

As technology continues to evolve, so does the way we live and interact with our homes. Smart home technology has quickly moved from being a luxury add-on to a desirable and often essential feature in many properties, including those in Ontario. From increased energy efficiency to enhanced security and convenience, the integration of smart tech is significantly transforming the real estate landscape.

At Magnolia Group Realty, we’re seeing a growing interest in homes equipped with state-of-the-art smart home features. Whether you’re buying, selling, or renovating, it’s important to understand how smart technology enhances the living experience and how it is shaping the future of Ontario real estate.

1. What is Smart Home Technology?

Smart home technology refers to a range of connected devices and systems that allow homeowners to control and monitor their home’s features remotely via smartphone or voice assistants. These technologies help automate everyday tasks, providing increased convenience, security, and efficiency.

Some common examples of smart devices include:

  • Smart thermostats (e.g., Nest or Ecobee) that control your home's temperature based on your preferences and schedule.

  • Smart lighting systems that can be dimmed, changed in color, or even programmed to turn on and off at specific times.

  • Smart security systems that feature cameras, alarms, smart locks, and video doorbells like Ring to enhance home safety.

  • Smart appliances that provide remote control over everything from your oven to your refrigerator.

  • Voice assistants like Amazon Alexa, Google Home, or Apple HomeKit that integrate with various devices for seamless control.

2. Why Smart Home Technology is on the Rise

Smart home technology has skyrocketed in popularity due to the significant benefits it offers, and there’s no sign of this trend slowing down in Ontario. Here's why:

  • Energy Efficiency and Cost Savings: Smart thermostats and lighting systems allow homeowners to optimize energy usage, leading to substantial savings on utility bills. For example, a smart thermostat can learn your schedule and automatically adjust the temperature, ensuring your home is always comfortable when you're there, but not wasting energy when you're away. In Ontario, where energy costs can be high, the potential savings from these systems are a huge draw for many buyers.

  • Enhanced Security: Smart security systems, such as cameras, motion detectors, and smart locks, offer unparalleled control over home safety. These systems can send instant notifications if something unusual is detected, and provide homeowners with real-time access to what’s happening at their property. Homebuyers in Ontario are increasingly seeking homes with these added layers of security, especially as remote monitoring becomes more convenient.

  • Convenience and Connectivity: Imagine walking into your home after a long day and having the lights turn on automatically, your favorite playlist start playing, and the thermostat adjust to your ideal temperature—all controlled by a voice command or preset schedule. Smart homes add an element of luxury, but they also make everyday tasks simpler. Integrated systems that link your home’s devices allow for streamlined, one-touch control, giving homeowners unparalleled convenience.

3. How Smart Technology is Influencing the Ontario Real Estate Market

As consumer demand for smart home features increases, homebuyers and sellers in Ontario are recognizing the added value that smart technology provides. For real estate buyers, this tech-forward approach means the ability to experience a level of convenience, energy efficiency, and security that was previously unavailable.

  • Increase in Property Value: Homes equipped with popular smart home features can increase in market value and attract more buyers. Sellers can use these features to justify a higher listing price by showing how they contribute to lower energy bills and provide added convenience and safety.

  • Appeal to Millennial Buyers: The millennial generation is drawn to smart homes as they appreciate technology-driven living spaces. As millennials make up a large portion of the current real estate market, homes with integrated smart technology often find a quicker buyer.

  • New Construction Homes: Builders are increasingly incorporating smart technology into newly constructed properties. When purchasing a brand-new home, potential buyers often expect these high-tech features to be part of the property, making smart technology a standard part of the Ontario real estate market.

4. Considerations for Ontario Homeowners

While integrating smart home technology offers numerous advantages, homeowners should also be mindful of a few important considerations:

  • Compatibility and Integration: It’s essential to ensure that the smart devices in your home are compatible with one another, and that the network or system you set up is easy to maintain and expand as needed.

  • Security and Privacy: Smart home devices are typically connected to the internet, making them vulnerable to cyber-attacks. It’s crucial to use strong, updated passwords and ensure your network is secure when using these devices.

  • Future-Proofing Your Home: As technology evolves, it’s a good idea to invest in smart systems that are scalable and can be easily upgraded. This allows your home to adapt and stay relevant as new smart technologies emerge.

5. Conclusion: The Future of Smart Homes in Ontario

Smart home technology is here to stay, and its growing popularity in Ontario real estate shows no sign of slowing down. For buyers and sellers, understanding these systems and how they impact the market is important. Whether you’re looking to buy a home with cutting-edge technology, or you’re interested in adding smart features to your own home to increase its market appeal, there are plenty of opportunities in Ontario’s real estate market to benefit from this trend.

At Magnolia Group Realty, we’re committed to providing you with the latest insights into how smart home technology is influencing the Ontario market. If you're interested in homes with smart features, or want to sell a property that's tech-forward, we can help you make the most of the growing demand for smart homes.

Read

Navigating the Luxury Real Estate Market in Waterloo Region | Magnolia Group Realty

Navigating the Luxury Real Estate Market in Waterloo Region | Magnolia Group Realty

The luxury real estate market in Waterloo Region has seen significant growth in recent years, attracting affluent buyers looking for spacious properties in prime locations. Known for its prosperous economy, innovation hubs, and beautiful landscapes, the region offers a compelling mix of urban and suburban luxury living. Whether you're buying, selling, or investing in the Waterloo Region luxury market, understanding the current trends and opportunities is essential. At Magnolia Group Realty, we’re here to provide the insights you need to successfully navigate this growing segment of the real estate market.

1. Demand for Luxury Homes in Waterloo Region

Waterloo Region has become a prominent destination for buyers seeking luxury properties, thanks to its dynamic blend of culture, education, and technology. Cities like Waterloo, Kitchener, Cambridge, and the surrounding rural areas are home to stunning, high-end homes that combine privacy, proximity to key amenities, and unparalleled natural beauty. Whether it's expansive country estates, waterfront properties, or ultra-modern homes, Waterloo Region offers a variety of luxury options.

Factors like remote work, the region's rising profile as a tech hub, and access to natural settings contribute to the growing demand for luxury real estate. Buyers looking to settle in the region are attracted to both its high-end urban developments and large, picturesque estates.

Tip for Buyers: Luxury buyers in Waterloo Region should be aware of highly desirable neighborhoods like Westmount, Old Westmount, Shantz Hill (Kitchener), Doon South, and Riverbend in Cambridge, where you’ll find many prestigious properties with ample land and access to luxury amenities.

2. Trends in Waterloo Region’s Luxury Market

  • Remote Work-Driven Growth: Like many regions in Ontario, Waterloo Region has witnessed an uptick in demand for larger homes with home offices, more living space, and outdoor amenities. Buyers are increasingly seeking properties offering privacy but also easy access to key areas, such as the University of Waterloo, Conestoga College, or Uptown Waterloo.

  • Eco-Conscious Luxury: Sustainable luxury is also a growing trend in the market. High-net-worth buyers are looking for homes with eco-friendly features, like solar panels, energy-efficient appliances, and high-quality insulation. A rising emphasis on sustainability means that modern luxury homes now include environmentally responsible technology as part of the luxury experience.

  • Waterfront and Scenic Views: Properties along Waterloo Region’s rivers and creeks, such as homes near the Grand River or those with views of lush forests, remain among the most sought-after in the region. Whether it’s a waterfront retreat or a countryside oasis, access to scenic landscapes continues to attract luxury buyers.

3. Investment Opportunities in Waterloo Region’s Luxury Market

  • Investment in Prestige Areas: Waterloo Region continues to evolve as a major economic hub. With the region becoming more recognized as a center for innovation, high-tech industries, and education, luxury homes in close proximity to Research and Technology Park in Waterloo and Cambridge’s Tech Sector present strong investment opportunities. These areas are home to professionals in the tech field, making proximity to work desirable for high-net-worth individuals.

  • Lakefront and Riverfront Properties: Consider lakefront or riverfront homes in neighborhoods like Cambridge or Elmira. With increasing demand for waterfront properties offering privacy and scenic views, investing in these prime locations may offer long-term capital appreciation while enjoying serene surroundings.

  • Luxury Condominiums: The demand for luxury condos in key urban areas within the region like Uptown Waterloo or Downtown Kitchener is growing steadily. High-rise and modern condominium units offer contemporary urban living, with amenities like gyms, concierge services, and spectacular views of the city skyline. These are appealing for luxury buyers looking for low-maintenance, high-convenience living in Waterloo Region’s bustling centers.

4. Buyer’s Perspective in the Luxury Market

For potential buyers, understanding the luxury home market in Waterloo Region is crucial for making a savvy investment:

  • Work with an Expert: A local real estate agent with specific experience in luxury properties can provide valuable insights and guidance when searching for high-end homes. Look for agents with deep knowledge of both urban and rural luxury property markets in Waterloo, Kitchener, Cambridge, and other key areas.

  • Be Ready for Multiple Offers: The demand for luxury homes means properties can move quickly, often with multiple offer scenarios. Having your financing pre-approved with a lender specializing in high-value loans is essential for making a strong offer in a competitive market.

5. Selling Your Luxury Property in Waterloo Region

If you are thinking about selling your luxury home, it’s important to strategically market your property:

  • Professional Marketing: Marketing your home using professional services like high-end photography, aerial drone shots, virtual tours, and well-crafted listings is key to attracting potential buyers.

  • Highlight Exclusive Features: Whether it's a large swimming pool, a home theatre, or expansive gardens, luxury homes often have standout features that make them unique. Highlighting these will set your home apart and increase its value.

  • Work with a Specialized Agent: Selling luxury real estate in the Waterloo Region requires experience in handling high-end properties. Working with a real estate team who understands your market and knows how to attract qualified buyers is essential for a successful sale.

Conclusion: Making the Most of Waterloo Region’s Luxury Real Estate Market

The luxury real estate market in Waterloo Region offers incredible opportunities for both buyers and sellers. With a booming tech-driven economy, scenic surroundings, and a growing interest in sustainable living, this market continues to thrive. Whether you’re seeking a private estate in the countryside or a luxury condominium in Kitchener, Magnolia Group Realty can help guide you through the process.

Our team of experts is here to offer you personalized real estate services and strategic insights into this exclusive market. Get in touch today to explore luxury properties in Waterloo Region!

Read

Exploring Mortgage Refinancing Options in Ontario | Magnolia Group Realty

Exploring Mortgage Refinancing Options in Ontario | Magnolia Group Realty

Homeownership is one of the most significant investments you'll ever make, and as the Ontario housing market fluctuates, refinancing your mortgage can be a smart way to take advantage of changing market conditions. Whether you're looking to save on monthly payments, consolidate debt, or tap into the equity in your home, mortgage refinancing offers a range of benefits. At Magnolia Group Realty, with a licensed Mortgage Agent on the team, we’re here to walk you through the various circumstances where refinancing makes sense and the different refinancing options available to homeowners in Ontario.

What is Mortgage Refinancing?

Mortgage refinancing is the process of replacing your existing mortgage with a new one, typically with different terms and conditions. This allows you to alter your mortgage to better align with your current financial goals, such as lowering monthly payments, reducing your interest rate, or adjusting the length of the loan.

When done properly, refinancing can help you achieve your financial goals, whether it’s saving money in the long run or taking advantage of your home’s increasing value.

When Should You Consider Refinancing Your Mortgage?

Refinancing isn’t always the right option for every homeowner, but there are several scenarios where it can be particularly advantageous. Here are some common situations where refinancing makes sense:

  1. Lowering Your Interest Rate

    • If mortgage interest rates have dropped since you took out your original loan, refinancing could allow you to lock in a lower rate, which could significantly lower your monthly payments and reduce the amount of interest you pay over the life of the loan. This can result in significant savings, especially in Ontario where rates fluctuate.

  2. Switching From a Variable to a Fixed Rate

    • A variable-rate mortgage can be great when rates are low, but when market conditions change, your payments may increase. Refinancing to a fixed-rate mortgage gives you the peace of mind of predictable payments throughout the loan term, which could be beneficial in times of rising interest rates.

  3. Accessing Home Equity

    • Over time, your property might appreciate in value, and with a mortgage refinance, you can tap into that equity through a cash-out refinance. Homeowners often choose this option to finance home improvements, pay down high-interest debt, or fund other investments.

  4. Consolidating Debt

    • If you have accumulated high-interest debts, refinancing your mortgage can allow you to consolidate them into a single loan at a lower interest rate. By consolidating your debts, you could lower your monthly payments and simplify your finances.

  5. Shortening Your Mortgage Term

    • Refinancing doesn’t always have to be about lowering payments. If you have additional funds or a higher income, refinancing to a shorter mortgage term (e.g., switching from a 30-year to a 15-year mortgage) will help you pay off your loan faster and save on interest costs over the life of the loan.

What Are the Different Types of Mortgage Refinancing Options in Ontario?

  1. Rate-and-Term Refinance

    • This is the most common type of refinance. As the name suggests, you’ll be changing the interest rate or the length of your mortgage term. This option is best for homeowners who want to lower their interest rate, adjust their term, or switch from a variable-rate to a fixed-rate mortgage.

  2. Cash-Out Refinance

    • A cash-out refinance is when you refinance for more than what you owe on the house and take the difference in cash. This option is often used by homeowners who want to access equity in their home to fund major expenses like home renovations or debt consolidation.

  3. Cash-In Refinance

    • If you’re in a strong financial position, you might choose to pay down a portion of your mortgage balance in exchange for a lower loan amount or a lower monthly payment. This can be a good way to reduce your interest payments if you have accumulated savings and want to build more equity in your property.

Costs and Considerations When Refinancing

Refinancing isn’t without costs. As you consider this option, be mindful of the fees associated with refinancing, which can include:

  • Appraisal fees (to determine the new value of your home)

  • Legal fees

  • Lender fees (such as discharge fees for the current mortgage)

  • Title insurance

Be sure to consider these costs and compare them against the potential savings from refinancing. If you plan to stay in the home for many years, refinancing could result in significant long-term savings.

Conclusion: Is Mortgage Refinancing Right for You?

Refinancing your mortgage in Ontario is a powerful tool to help you achieve your financial goals, whether it’s lowering your monthly payments, paying off your mortgage faster, or accessing your home equity. However, before moving forward, be sure to evaluate the benefits and costs of refinancing in your particular situation.

At Magnolia Group Realty, our team is here to help you make informed decisions throughout your homeownership journey. While we’re not mortgage brokers, we can help connect you with trusted financial professionals to guide you through the refinancing process.

Ready to explore your refinancing options? Contact Magnolia Group Realty today, and let’s ensure you make the right decision for your future!

Read

2025 Real Estate Market Trends in Ontario: What Buyers and Sellers Need to Know | Magnolia Group Realty

2025 Real Estate Market Trends in Ontario: What Buyers and Sellers Need to Know | Magnolia Group Realty

The Ontario real estate market has experienced many fluctuations over the years, and 2025 is expected to bring some notable trends that both buyers and sellers should be aware of. Whether you're looking to purchase your first home or are considering selling your property, understanding the evolving market conditions can help you make informed decisions. At Magnolia Group Realty, we’re here to break down the key trends shaping the Ontario real estate market in 2025.

1. Interest Rates: Impact on Buyer’s Power

In early 2025, interest rates are anticipated to remain higher than in previous years. This impacts how much buyers can afford to borrow, potentially cooling down the market for those relying on mortgage financing. For buyers, it’s crucial to adjust your budget and pre-approval process to better reflect higher borrowing costs.

Tip for Buyers: Consider locking in a mortgage rate if you are pre-approved now. Start thinking about affordability with higher rates in mind, and budget for larger monthly payments.

For sellers, homes priced too high might sit longer on the market due to higher borrowing costs, meaning competitive pricing will be key.

2. Supply and Demand: A Tight Market

Despite fluctuating interest rates, the supply of homes in Ontario remains constrained, particularly in major urban areas like Toronto and Ottawa. With housing inventory at historically low levels and demand still strong, many sellers may find themselves in a position where multiple offers drive prices up.

Tip for Sellers: Pricing your home right from the start is essential to generating interest and competing with similar listings. You could see multiple bids on your property if you hit the right price point.

For buyers, it’s critical to move fast on properties that meet your needs. With competition increasing, you might face bidding wars.

3. Increased Interest in Smaller Towns and Suburbs

As remote work remains a significant part of the work landscape in 2025, smaller towns and suburban areas in Ontario are experiencing increased demand. Many buyers are looking to relocate from crowded urban centers like Toronto to quieter, more affordable neighborhoods within driving distance of the city.

This trend is contributing to rising prices in markets that were traditionally considered more affordable. Areas such as Kitchener-Waterloo, Barrie, and Niagara have seen notable growth in both demand and property values.

Tip for Buyers: If you’re open to relocating, consider the lifestyle benefits that smaller communities and suburbs can provide—lower cost of living, larger properties, and growing local amenities.

For sellers in smaller cities, there may never be a better time to list your home. The increased demand for properties outside of major urban centers provides an opportunity for sellers to take advantage of the buyer interest in these regions.

4. Sustainability and Eco-Friendly Features

As environmental awareness continues to rise, more buyers are looking for sustainable homes. Green certifications, energy-efficient appliances, solar panels, and environmentally-conscious materials are becoming highly sought-after features in Ontario homes. Buyers are recognizing the long-term savings on energy costs and the value of a sustainable lifestyle.

Tip for Buyers: Consider purchasing properties with eco-friendly features, as they not only reduce your environmental impact but also potentially save you money in utility costs in the long run.

Tip for Sellers: Investing in green renovations or highlighting energy-efficient upgrades can help your listing stand out. Green features are attractive to buyers, especially those looking for energy savings and sustainable living.

5. Luxury Market Growth

Luxury real estate in Ontario, especially in areas such as Toronto, Oakville, and King City, is projected to grow. As high-net-worth individuals seek more spacious properties, the luxury market remains robust, with demand for private estates, waterfront properties, and high-end urban condos on the rise.

Tip for Sellers: If your home falls into the luxury category, the 2025 market is expected to attract well-qualified buyers who are eager for exclusivity and unique features. Ensure your home is staged to highlight its upscale features.

For buyers, the opportunity to invest in the luxury market is still promising, especially in the wake of rising market demand in highly desirable areas.

2025 Market Predictions at a Glance:

  1. Interest Rates: Likely to stay elevated, impacting buyers’ borrowing power.

  2. Demand for Suburbs: Increased interest in smaller towns and suburban markets due to remote work.

  3. Low Inventory: Continued low housing inventory leading to high competition among buyers.

  4. Eco-Friendly Homes: A focus on sustainable, energy-efficient properties.

  5. Luxury Market: Strong demand for luxury homes in Ontario’s prime locations.

Conclusion: Navigating the 2025 Real Estate Market

As the Ontario real estate market evolves in 2025, it’s crucial for both buyers and sellers to stay informed about these market shifts. Magnolia Group Realty is dedicated to guiding you through this changing landscape, whether you're looking to find your dream home or take advantage of the current market trends as a seller.

Get in touch with us today for expert advice tailored to the unique real estate dynamics in Ontario’s 2025 market.

Read